Your Kid's College Fund Could Help You Buy Your First Home
Lisa Mailhot | August 14, 2026
Buyers
Lisa Mailhot | August 14, 2026
Buyers
Disclaimer: This blog is for informational purposes only and may reference third-party sources, including quotes or data used verbatim with proper credit. All efforts are made to ensure originality and avoid plagiarism. Readers should verify details independently and consult a licensed professional before making real estate decisions.
For years, 529 college savings accounts have had one job: covering tuition, books, and other education costs. If you tried to use that money for anything else, you were hit with income taxes plus a 10 percent penalty on the earnings portion of the withdrawal. But a new bipartisan proposal in Congress wants to change that, and it could hand first-time buyers a fresh source of down payment cash they never thought to consider.
In February 2026, U.S. Representatives Tom Barrett, Tracey Mann, Mark Alford, and Lou Correa introduced the First-Time Homebuyer Empowerment Act, known as H.R. 7468. A companion bill, S. 5227, followed in the Senate from Senators Jon Husted and Michael Bennet. The goal behind both versions is simple: let families put leftover college savings toward a first home instead of leaving that money locked away or facing a tax hit to access it.
If passed, the legislation would allow beneficiaries of long-held 529 accounts to withdraw up to $35,000 tax free specifically to buy their first house. Supporters of the bill include the National Association of Realtors, the National Association of Homebuilders, the Mortgage Bankers Association, and several state Realtor associations, including the California Association of Realtors.
The proposed rules come with some important guardrails. The 529 account would need to have been open and maintained for at least 15 years, and any contributions made within the last five years, along with their earnings, would not count toward the withdrawal. The funds would need to go toward the purchase within 60 days, and the buyer would have to qualify as a first-time homebuyer.
There is also a shared lifetime cap to keep in mind. The $35,000 limit is combined with the existing SECURE 2.0 provision that already lets savers roll unused 529 funds into a Roth IRA, so every dollar used for a Roth rollover reduces what is available for a home purchase, and vice versa. If a home purchase does not go through, buyers would get 120 days to return the funds to a 529 or ABLE account without penalty. And if the home is sold or the buyer stops living in it within five years, the tax benefit gets clawed back on a sliding scale, reduced by 20 percent for each full year of ownership.
Saving for a down payment is one of the toughest hurdles for first-time buyers anywhere, and Orange County is no exception. With home prices here running well above the national average, every legitimate source of down payment funds matters. Families who have been diligently saving for a child's education, only to end up with more in the account than tuition required, could suddenly have a practical way to redirect that money toward homeownership instead of watching it sit idle or paying penalties to touch it.
This kind of legislation also reflects a broader trend I have been watching in the market: lawmakers and industry groups looking for creative ways to chip away at the affordability gap, especially for buyers who feel priced out of neighborhoods they grew up in. Whether it is expanded down payment assistance programs, adjusted loan limits, or proposals like this one, the direction is the same. Give buyers more tools to compete.
It is important to remember this is still a bill, not a law. It still needs to move through committee, pass both chambers of Congress, and be signed before any of these rules take effect. If you are currently saving in a 529 and eyeing a first home purchase, this is worth tracking, but you should not build your entire down payment strategy around legislation that has not been finalized.
In the meantime, it is a good moment to sit down and take stock of what savings and assistance programs are already available to you, from FHA loans with lower down payment requirements to state and local first-time buyer programs here in California. A clear picture of your options now puts you in a stronger position no matter what happens with this bill.
Whether or not this bill becomes law, the bigger takeaway is this: there are more paths to homeownership than most buyers realize, and the landscape keeps shifting in ways that can work in your favor if you know where to look. If you are thinking about buying your first home in Orange County, or you simply want a clear-eyed read on how proposals like this one could affect your timeline and your budget, I would love to help you map out a plan. Reach out to me at Whitestone Real Estate, and let's turn your homeownership goals into a real strategy.
Reference: Navera, T. (2026, February). Should you use a 529 college savings account for a down payment on your first home? Realtor.com.
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
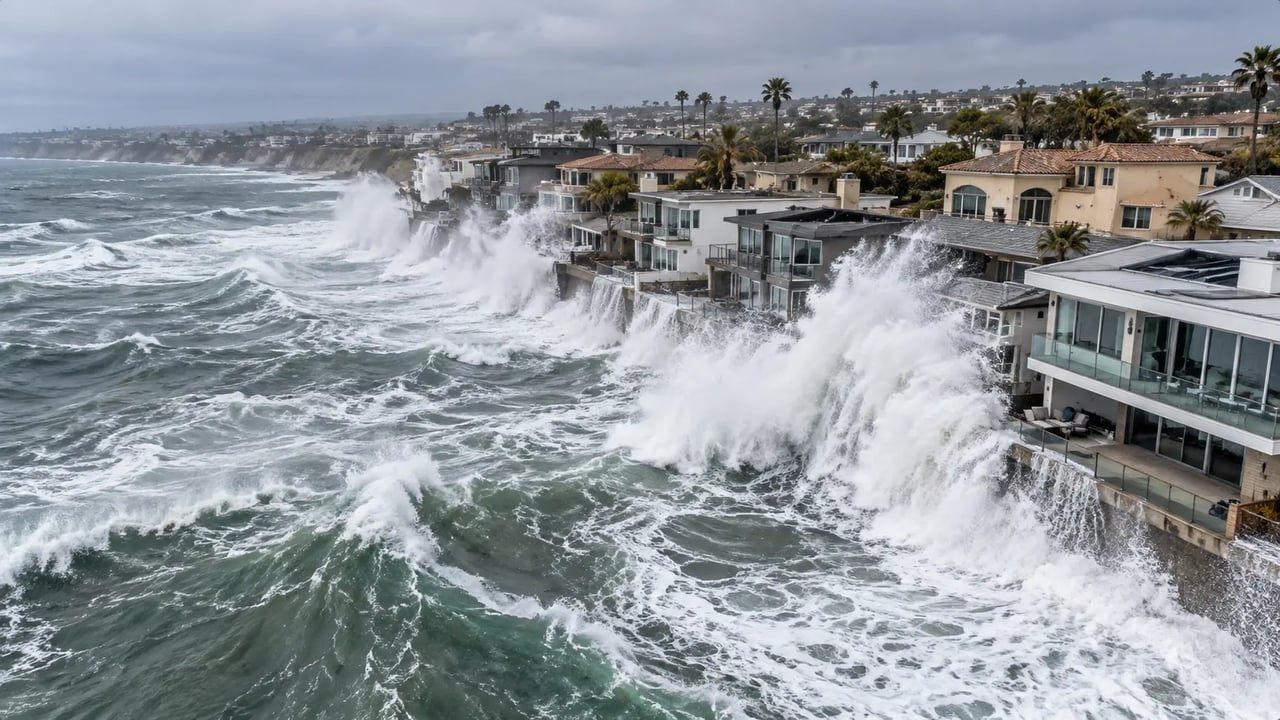
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663
