Why Now Is the Right Time to Open a Home Equity Loan Before 2024 End
Lisa Mailhot | November 7, 2024
Buyers

Lisa Mailhot | November 7, 2024
Buyers
In today’s shifting financial landscape, exploring ways to fund home improvements or other expenses often leads homeowners to consider a home equity loan. This option has been a cost-effective way to borrow, especially as other credit types have seen rising rates due to inflation. While credit card and personal loan rates have surged, home equity loans and HELOCs (Home Equity Lines of Credit) have remained comparatively affordable due to the home serving as collateral. With the Federal Reserve’s recent rate cut in September—and another one anticipated soon—borrowing against your home has become even more attractive.
But there’s an additional benefit to opening a home equity loan before the year ends: potential tax savings. The IRS allows borrowers to deduct interest on home equity loans used for qualifying home improvements as long as the loan is secured by the home in question. This tax advantage can significantly affect your upcoming tax return, provided you use the funds before December 31, 2024.
Time is of the essence, as processing a home equity loan can take several weeks. By acting soon, you increase the likelihood of receiving your funds before the end of the year, allowing you to benefit from the tax deduction on any eligible home improvements completed before then. Waiting could mean missing out on these valuable savings, especially if your disbursement date slips into January. By securing your loan now, you’re setting up a financial advantage that could alleviate some of your 2024 tax burden while supporting your home projects.
If you plan on taking on home projects and could use extra financial support, a home equity loan might be your ideal solution—especially before December 31. Whether you’re interested in a HELOC or a lump-sum home equity loan, now is the time to act to maximize tax benefits. Ready to explore options in Orange County? Let’s connect!
Record 10% of first-time buyers paid all cash and the median age hit 40. See what NAR’s 2026 data means for Orange County buyers and sellers.
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
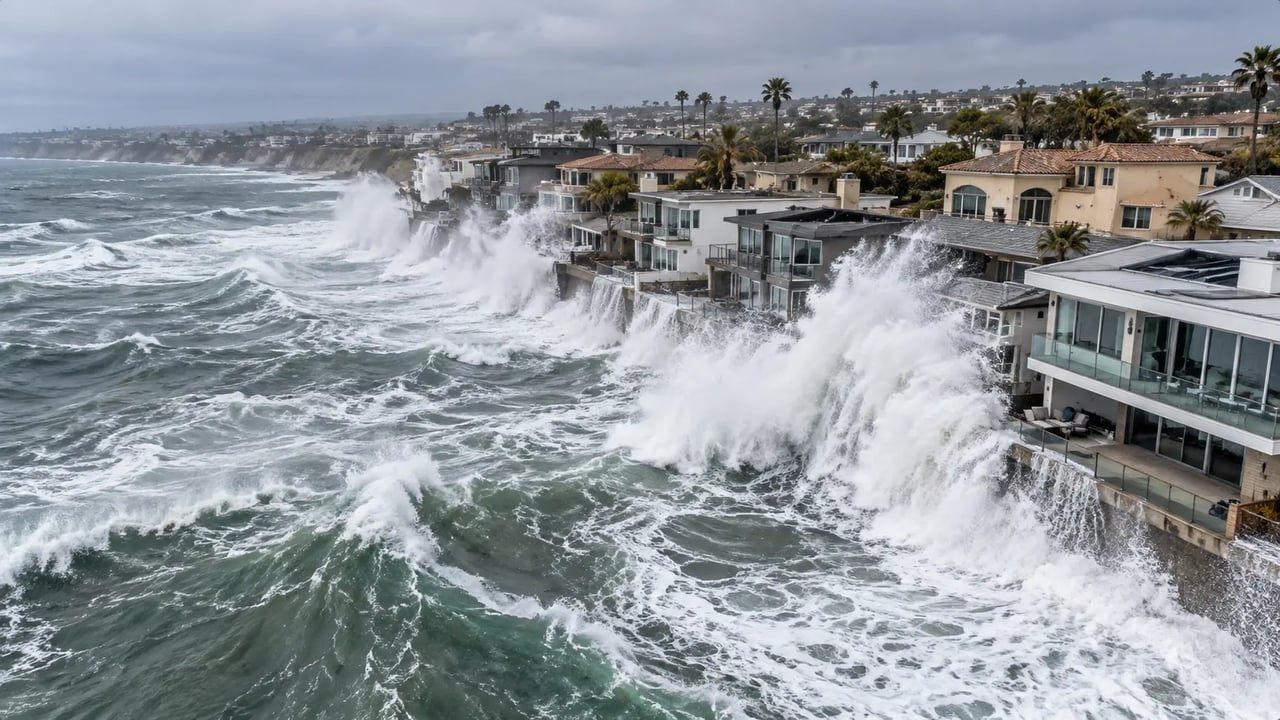
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa
Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663
