2 Smart Ways to Use Your Home Equity This December
Lisa Mailhot | December 3, 2024
Agents
Lisa Mailhot | December 3, 2024
Agents
As December rolls in, many homeowners are exploring ways to leverage their home equity for financial flexibility. With the average homeowner sitting on roughly $319,000 in equity, according to the November 2024 ICE Mortgage Monitor, it’s tempting to tap into this resource. But home equity is not a “one-size-fits-all” financial solution—it demands a strategic approach. Below, we’ll guide you through two safe uses for your home equity and highlight two potentially risky ones to steer clear of.
Home Repairs and Renovations
Investing in home repairs and renovations is one of the wisest ways to utilize your home equity. Improvements that enhance your home’s value can boost your property’s equity and provide a tax advantage. For instance, IRS-eligible projects can allow you to deduct interest from your home equity loan or HELOC on your tax return. You might even secure a partial deduction for this tax season by acting now. Waiting, however, could delay these benefits until 2026.
Consolidating High-Interest Debt
With holiday spending surging, consolidating high-interest debt through your home equity can be a financially sound move. Home equity loans and HELOCs typically have interest rates under 9%—much lower than personal loans (averaging 13%) or credit cards (averaging over 23%). This approach can ease your financial burden and streamline payments, setting you up for a stronger start to 2025.
Holiday Spending
Using home equity to fund holiday purchases may seem convenient but could lead to regret. A HELOC, which functions like a credit card, might tempt you to overspend on gifts or other seasonal expenses. Instead of creating short-term joy, this decision can harm your long-term financial health. Home equity should be reserved for meaningful investments, not fleeting festivities.
Purchasing Depreciating Assets
Using home equity to buy items like vehicles or other assets that lose value over time is rarely advisable. This approach doesn’t maximize your home equity’s potential even with lower interest rates. Instead, focus on leveraging it to appreciate assets or investments that contribute to your financial growth.
Home equity offers a powerful financial tool—but only when used wisely. You can safeguard your financial health by prioritizing smart strategies like home improvements and debt consolidation while avoiding risky moves like overspending or buying depreciating assets. Ready to make your next move in Orange County? Let’s connect and discuss your goals today!
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
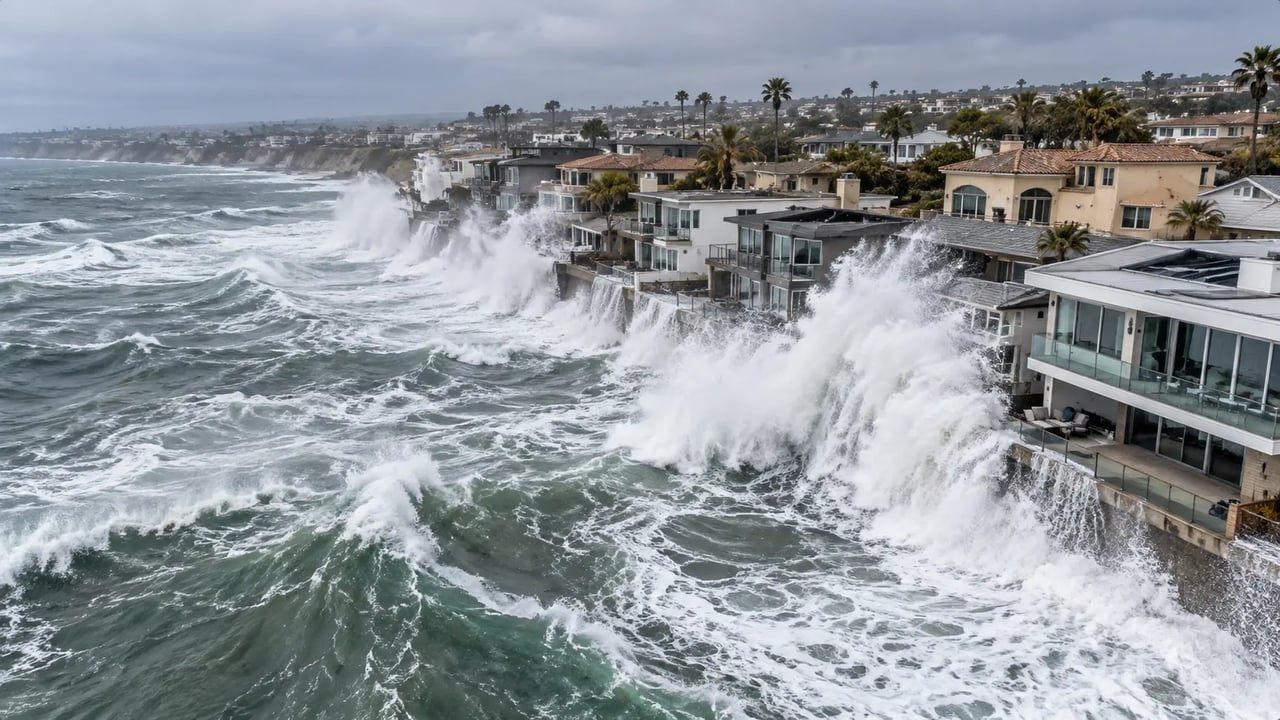
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663