Longtime Homeowner? This Hidden Tax Could Cost You Thousands
Lisa Mailhot | June 25, 2025
Buyers
Lisa Mailhot | June 25, 2025
Buyers
Disclaimer: This blog is for informational purposes only and may reference third-party sources, including quotes or data used verbatim with proper credit. All efforts are made to ensure originality and avoid plagiarism. Readers should verify details independently and consult a licensed professional before making real estate decisions.
Millions of Americans are facing an unexpected consequence of owning a home for too long: a hidden home equity tax. "Today, roughly 1 in 3 homeowners—nearly 29 million households—have built up more home equity than the federal capital gains tax exclusion for single filers protects when they sell their primary home." For homeowners in booming markets like Orange County, the longer you stay and the more your property appreciates, the more likely the IRS will take a cut when you sell.
This tax isn’t just about dollars and cents—it impacts financial planning, retirement strategies, and access to housing inventory for future generations.
This issue began back in 1997 when Congress overhauled the rules for taxing profits from selling a primary residence. Before then, sellers could defer capital gains if they upgraded to a more expensive home. That system was cumbersome and confusing.
“It was a compliance mess,” said Evan Liddiard, director of tax policy at the National Association of Realtors®. So, Congress introduced a more straightforward exclusion: up to $250,000 for single filers and $500,000 for married couples. But here’s the catch—those amounts were never indexed for inflation.
Since 1997, home prices have soared over 260%, yet the tax thresholds remain unchanged. If the law had kept up, the exclusion would now be around $660,000 for individuals and $1.32 million for couples.
Those most affected are the homeowners who’ve stayed the longest—especially in states like California. In fact, "about 31% in California could get hit" by this outdated exclusion limit. That means thousands of Orange County homeowners may be on the hook for tens—or even hundreds—of thousands in unexpected taxes when they sell.
The average federal tax bill for these homeowners sits around $35,000, but in high-value states, that figure can be significantly higher. In Wyoming, the average gain exposed to taxation for those over the joint filer cap is nearly $500,000.
What was once a wise financial move—paying off a mortgage and building equity—can now feel like a penalty. “This really is a tax on home equity,” explains Shannon McGahn, executive VP and chief advocacy officer at the NAR. Homeowners nearing or past retirement are especially vulnerable. Rather than sell and face a steep tax bill, many simply stay put—even if they no longer need the space or can barely manage the upkeep.
This creates a troubling ripple effect: fewer family-sized homes on the market, tighter inventory, and higher prices for younger buyers trying to get in.
Homeowners are stuck between a rock and a hard place. Sell, and you might face a six-figure tax bill. Stay, and rising property taxes could eat into your budget—especially if you're on a fixed income. Some homeowners are even living in just part of their house to avoid selling.
“We hear reports... some of these folks have moved to the main floor of their home... because they’re too feeble to do so,” said Liddiard. And yet, they refuse to sell because their heirs can receive a stepped-up basis, avoiding the capital gains tax altogether.
Without legislative change, this issue will only worsen. Projections show that by 2035, over 90% of homeowners in 13 states could face capital gains taxation on home sales. A bipartisan proposal, the More Homes on the Market Act, aims to double the exclusion and tie it to inflation, potentially easing the burden on families across Orange County and the nation.
In the meantime, advocacy and awareness are key. “The more people know that this is coming, the more their voices can be heard,” McGahn emphasizes.
The hidden home equity tax is quietly reshaping the real estate landscape in Orange County and beyond. If you’ve been in your home for decades or are planning your next move, understanding your potential tax liability is more important than ever. At Whitestone Real Estate, we help clients navigate the ins and outs of buying, selling, and protecting their equity. If you’re thinking about making a move, downsizing, or simply want to explore your options in today’s market, let’s connect and create a strategy that works for your future.
Reference: Conte, A. (2025, June 24). Homeowners face a stiff penalty for staying in their homes too long—a hidden home equity tax. Realtor.com.
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
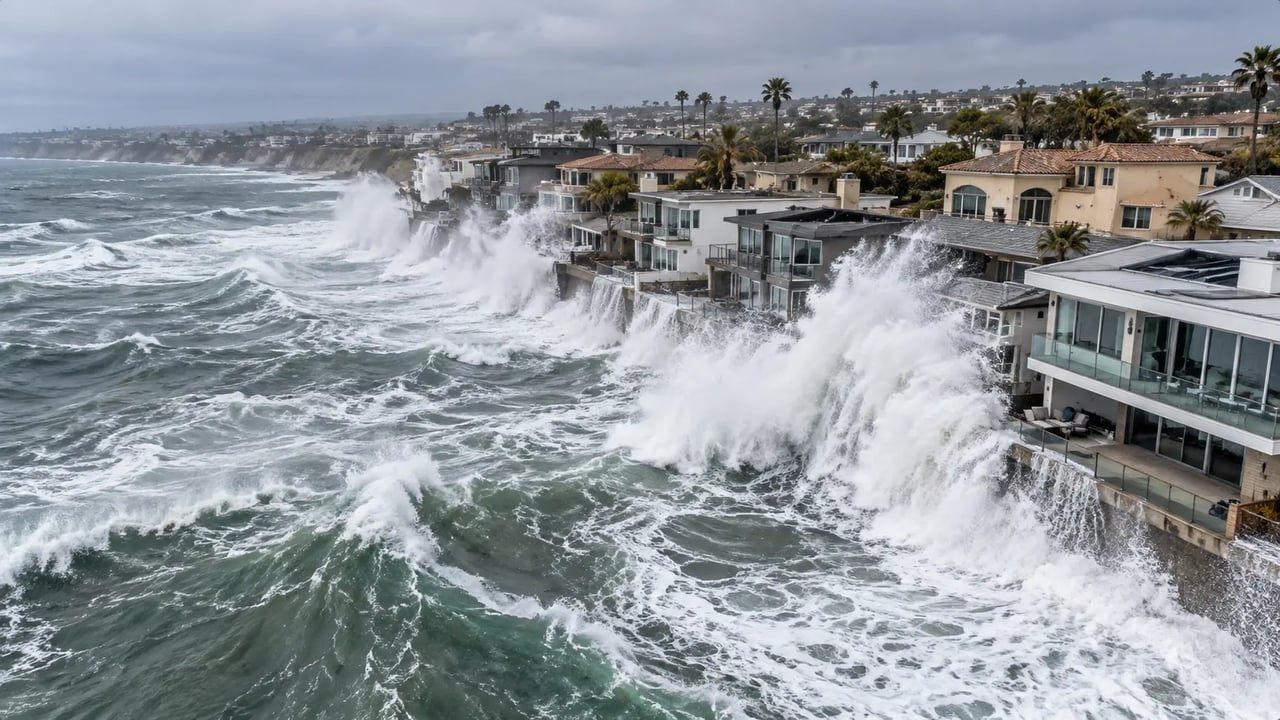
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663