How to Navigate Low Mortgage Rates for Maximum Benefit
Lisa Mailhot | August 21, 2024
Sellers
Lisa Mailhot | August 21, 2024
Sellers
The dip in mortgage rates has opened a window of opportunity for homeowners considering refinancing. This blog goes beyond the basics, diving deep into the critical factors like loan terms, credit scores, and property values that impact your refinancing decision. Whether you're looking to lower your payments or tap into home equity, this guide is for you.
Loan terms are not just about the duration; they dictate your financial commitment over the years. Refinancing to a shorter term might raise your monthly payments but save you a significant amount on interest, making it a wise choice if you can afford the increased monthly outlay. On the other hand, lengthening the term of your loan can reduce your monthly payments, but it will result in a higher total interest cost over the duration of the loan.
Your credit score is crucial in determining the interest rates available to you. A better credit score can secure lower interest rates, enhancing the advantages of refinancing. It's advisable to check your credit score and possibly improve it before applying for refinancing to secure the best terms possible.
Current property values greatly influence refinancing options. An increase in your home’s market value can boost your equity, possibly allowing you to eliminate private mortgage insurance (PMI) costs if your equity is now over 20%. This can be a significant financial relief and add to the benefits of refinancing.
This guide is particularly valuable for:
Start by evaluating your current mortgage, noting your interest rate, remaining term, and monthly payment. Compare these with potential new offers to see if refinancing could be financially advantageous.
Always consult with a mortgage advisor to understand the specific impacts on your financial situation. They can provide insights into whether it’s better to lock in a rate now or wait for further decreases.
Refinancing can be a powerful tool for managing your mortgage costs and terms. With rates at a historical low, now might be the perfect time to consider your options. If you're based in Orange County and are contemplating refinancing, let's connect to explore how you can benefit from the current rates.
Record 10% of first-time buyers paid all cash and the median age hit 40. See what NAR’s 2026 data means for Orange County buyers and sellers.
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
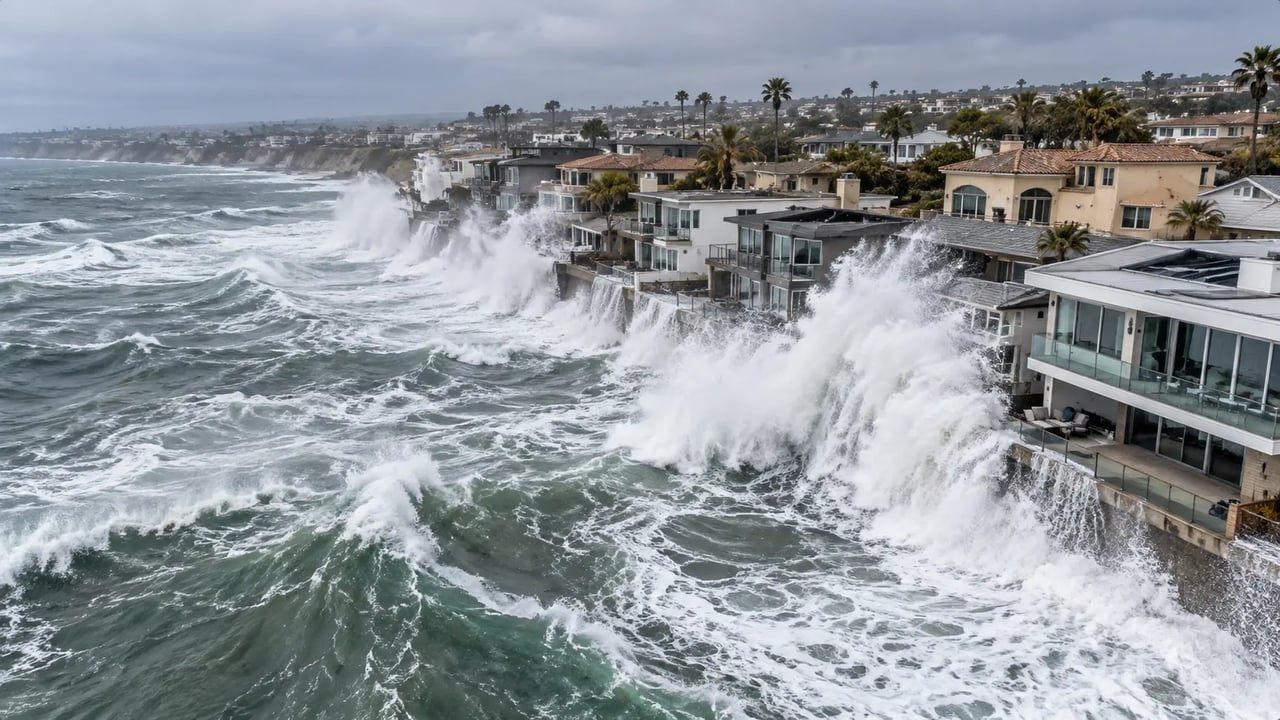
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663