Understanding HEAs vs. HELOCs and Home Equity Loans
Lisa Mailhot | July 19, 2024
Sellers
Lisa Mailhot | July 19, 2024
Sellers
When you need cash and are thinking about tapping into your home equity, one option that might not be on your radar is a Home Equity Agreement (HEA). Here’s why an HEA could be a game-changer for you, especially compared to the more familiar Home Equity Line of Credit (HELOC) or home equity loan.
A HELOC offers flexibility by allowing you to borrow as much or as little as you need, accruing interest only on the portion you use. This can be a great option for home renovation projects where the costs are unpredictable. However, HELOCs come with a variable interest rate and a typical repayment term of just 10 years.
Home equity loans provide a lump sum with a fixed interest rate, usually spread over 30 years. This can be ideal for homeowners who prefer a predictable monthly payment plan.
An HEA stands out because it doesn’t require monthly payments. Instead, you repay the loan and a percentage of your home’s future appreciation when you sell. This makes HEAs particularly appealing if you have a lower credit score, are self-employed, or have a higher debt-to-income ratio.
“An HEA offers homeowners in various financial circumstances the opportunity to borrow a lump sum of interest-free money,” says Doug Perry, a strategic financing adviser at Real Estate Bees. This type of loan is becoming increasingly popular due to its relatively low barrier to entry.
Despite its advantages, an HEA has some potential drawbacks. They are not yet available in every state and are typically serviced by private investment companies such as Unlock, Point, and Unison. There’s also an upfront fee of 3% to 5% and an appraisal fee.
You need to be comfortable with the terms, which might include restrictions on selling your home or making significant renovations. Plus, if you decide not to sell your home, you’ll still need to repay the amount borrowed at the end of the loan term, which can be between 10 and 30 years.
“They’re like reverse mortgages for people that aren’t old, because you don’t have payments on them,” says Mark McDonough of Assume Loans.
If you’re thinking about leveraging your home equity and want to explore flexible financial solutions, an HEA might be the right choice for you. Always ensure you fully understand the terms and consider whether you’re ready to give up a portion of your home’s future equity for immediate cash. If you're looking to move to Orange County, let's connect!
Reference: Gerstein, J. (2024, July 8). What Is an HEA? Home Equity Agreement vs. HELOC: The Pros and Cons, Explained. Realtor.com.
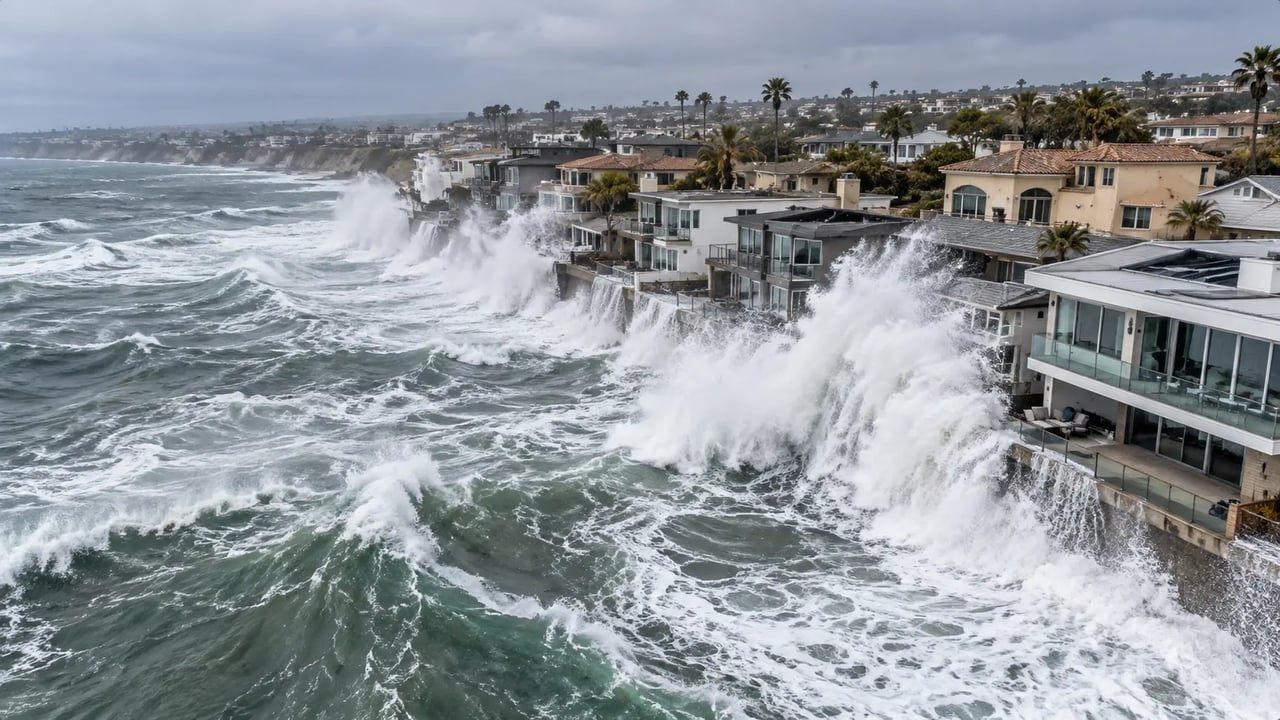
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Housing costs are the top concern for young voters heading into the 2026 midterms. See what it means for Orange County buyers and sellers.
Portable mortgages are back in Congress, but experts see big hurdles. Here is what Orange County buyers and sellers should know.
Tropical Storm Rachel flooded Newport Beach’s Balboa Peninsula. Here is what Orange County buyers and sellers should know about coastal living.
Record heat, wildfires and rising insurance costs are reshaping California moves. See what it means for Orange County buyers and sellers.
Rates above 7.5% are squeezing young voters. See what the affordability squeeze means for Orange County buyers and sellers.
Things to do in Orange County Oct 8 to 11, from Carnival Colossal and Margaret Cho to Irvine Global Village Festival and Chili at the Beach.
Price cuts hit a record September high nationwide. See what Redfin's new data means for Orange County buyers and sellers heading into fall.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa
Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663