Can You Really Pay Your Mortgage With a Credit Card?
Lisa Mailhot | March 12, 2025
Sellers

Lisa Mailhot | March 12, 2025
Sellers
You can use a credit card to pay for almost anything these days—utilities, taxes, medical bills—but when it comes to your mortgage, things get a bit tricky. Historically, paying your mortgage with a credit card has been considered a big no-no. But now, new options are popping up, making this once-taboo strategy a possibility.
The question is, should you do it?
Let’s break down why paying your mortgage with a credit card has been frowned upon, how the landscape is changing, and whether this option could work for you.
Most mortgage lenders don’t accept credit card payments directly. Why? Because they don’t want to cover the steep transaction fees, which can be as high as 3.5%.
But this reluctance might actually protect homeowners. Financial experts, like Andrea Woroch, warn that "using a credit card to pay your mortgage is a bad idea" for a few key reasons:
Higher Interest Rates: Credit card interest rates typically soar much higher than mortgage rates. "You run the risk of accruing high-interest debt in the event you can't pay your bill off in full," Woroch explains.
Credit Score Impact: Charging large amounts to your credit card can negatively impact your credit utilization ratio, which could drag down your credit score.
Potential for Debt: If you can’t pay off your credit card balance right away, you could find yourself sinking into a cycle of high-interest debt.
Still, many people are drawn to the perks—like cash back and travel rewards—that credit cards offer. So, is there a safe way to do it?
If you’re determined to explore this option, there are some platforms and services that can help you pay your mortgage with a credit card—while navigating around lender restrictions.
Plastiq acts as a middleman between you and your mortgage lender. Here’s how it works:
You sign up for a free account and link your credit or debit card.
Plastiq pays your mortgage company directly via ACH, wire transfer, or check.
You pay a 2.9% processing fee on each transaction.
While convenient, that 2.9% fee can add up quickly—so it’s only worth it if the rewards outweigh the costs.
The Mesa Homeowners Card takes a different approach. Instead of paying your mortgage with a credit card, you link your mortgage payment bank account to Mesa’s app. They verify your payment and reward you with points—without putting the actual charge on your card.
Earn one point per dollar on your monthly mortgage payments.
No annual fee, but be mindful of the 25.24% APR on other purchases.
This option lets you collect rewards without the risk of carrying high-interest debt.
Originally designed for renters, Bilt is expanding its perks to homeowners. Soon, Bilt cardholders will be able to earn points on mortgage payments—without incurring extra fees.
No annual membership fee.
APR ranges from 20.49% to 28.49% based on creditworthiness.
Bilt’s expansion into mortgages could be a game-changer for rewards seekers.
Like most financial decisions, using a credit card for your mortgage has its ups and downs.
Rewards Points & Perks: Earn cash back, travel rewards, or other perks on a large recurring expense.
Convenience: Manage your bills in one place and extend your payment timeline if needed.
Promotional Offers: Take advantage of 0% APR offers for a limited time, making it cheaper to carry the balance temporarily.
High Interest Rates: Unless you pay your balance in full, interest charges can quickly outweigh any rewards.
Fees: Platforms like Plastiq charge fees (up to 2.9%) that can reduce or eliminate the value of your rewards.
Credit Score Risks: Large charges can spike your credit utilization ratio, negatively impacting your credit score.
Andrea Woroch sums it up best: "When credit cards are used wisely, they can boost your budget through robust reward programs. The key is to pay off your monthly balance immediately if you can."
Paying your mortgage with a credit card is possible—but it comes with risks. If you’re disciplined and strategic, you can leverage rewards without falling into a debt trap. But if you’re not careful, high fees and interest rates could outweigh the benefits.
Considering a move to Orange County? At Whitestone Real Estate, we are committed to providing expert guidance to help you make informed decisions—whether it’s securing your ideal home or optimizing your mortgage strategy. Let’s discuss how we can turn your homeownership aspirations into reality with a seamless and strategic approach.
Reference: Taylor, J. (2025, February 24). Can I pay my mortgage with a credit card? Getty Images.
Portable mortgages are back in Congress, but experts see big hurdles. Here is what Orange County buyers and sellers should know.
Tropical Storm Rachel flooded Newport Beach’s Balboa Peninsula. Here is what Orange County buyers and sellers should know about coastal living.
Record heat, wildfires and rising insurance costs are reshaping California moves. See what it means for Orange County buyers and sellers.
Rates above 7.5% are squeezing young voters. See what the affordability squeeze means for Orange County buyers and sellers.
Things to do in Orange County Oct 8 to 11, from Carnival Colossal and Margaret Cho to Irvine Global Village Festival and Chili at the Beach.
Price cuts hit a record September high nationwide. See what Redfin's new data means for Orange County buyers and sellers heading into fall.
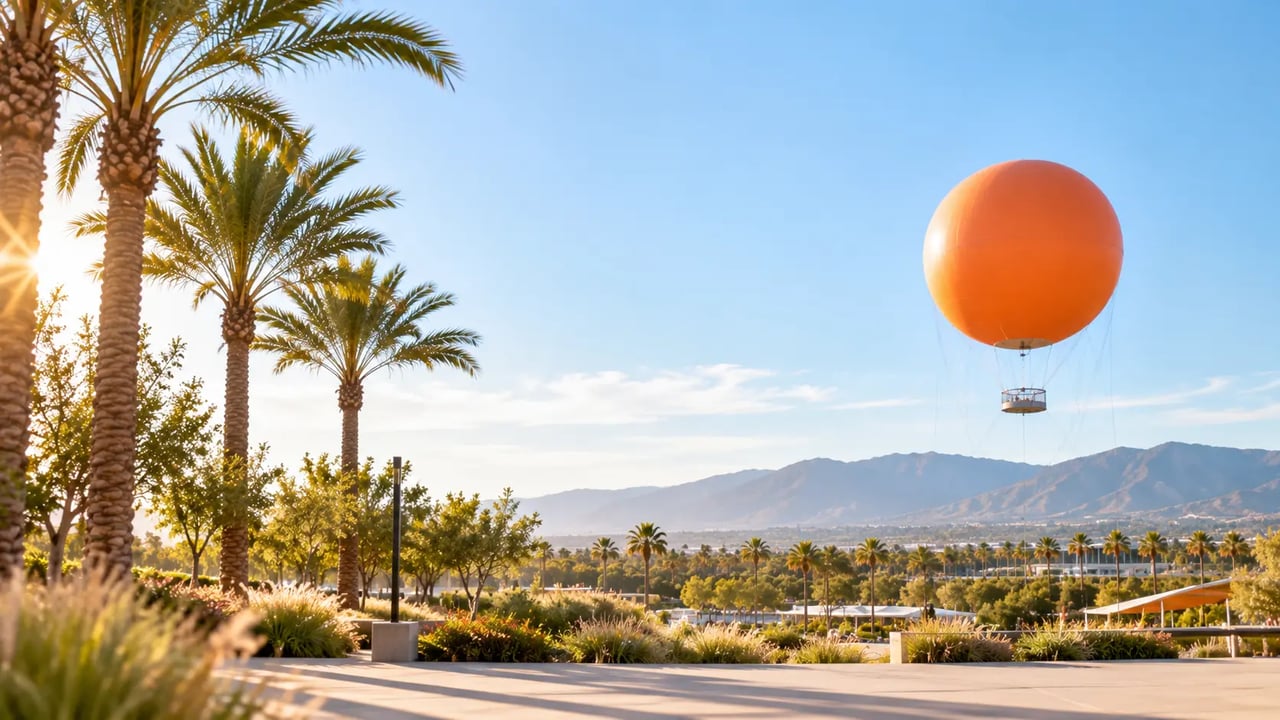
The Irvine Global Village Festival turns 25 on Oct. 10 at the Great Park with global food, music, dance and family fun in Orange County.
Housing affordability hit a 21-year low as the Fed signals more rate hikes. Here is what Orange County buyers and sellers should know.
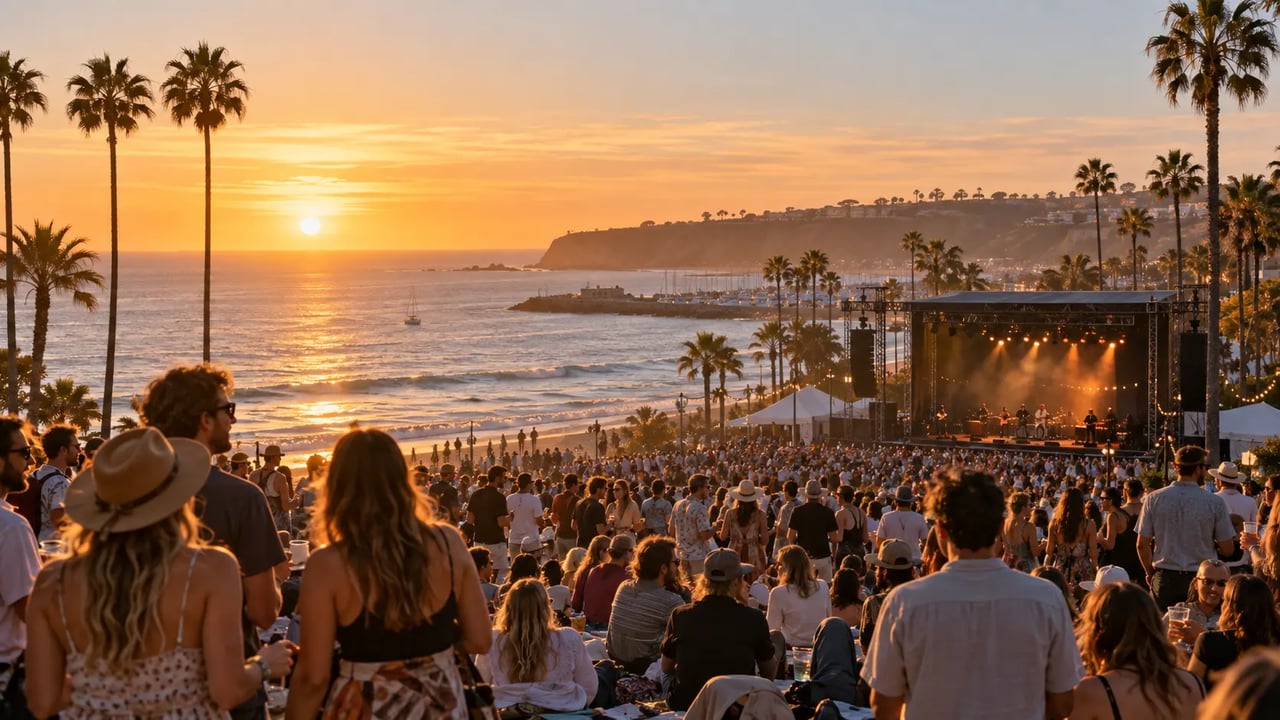
Ohana Festival returns to Doheny State Beach in Dana Point, September 25 to 27, with Pearl Jam, Maná and more. Your Orange County event guide.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa
Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663