Is Your Home Insurance Ready for a Disaster?
Lisa Mailhot | May 13, 2025
Buyers
Lisa Mailhot | May 13, 2025
Buyers
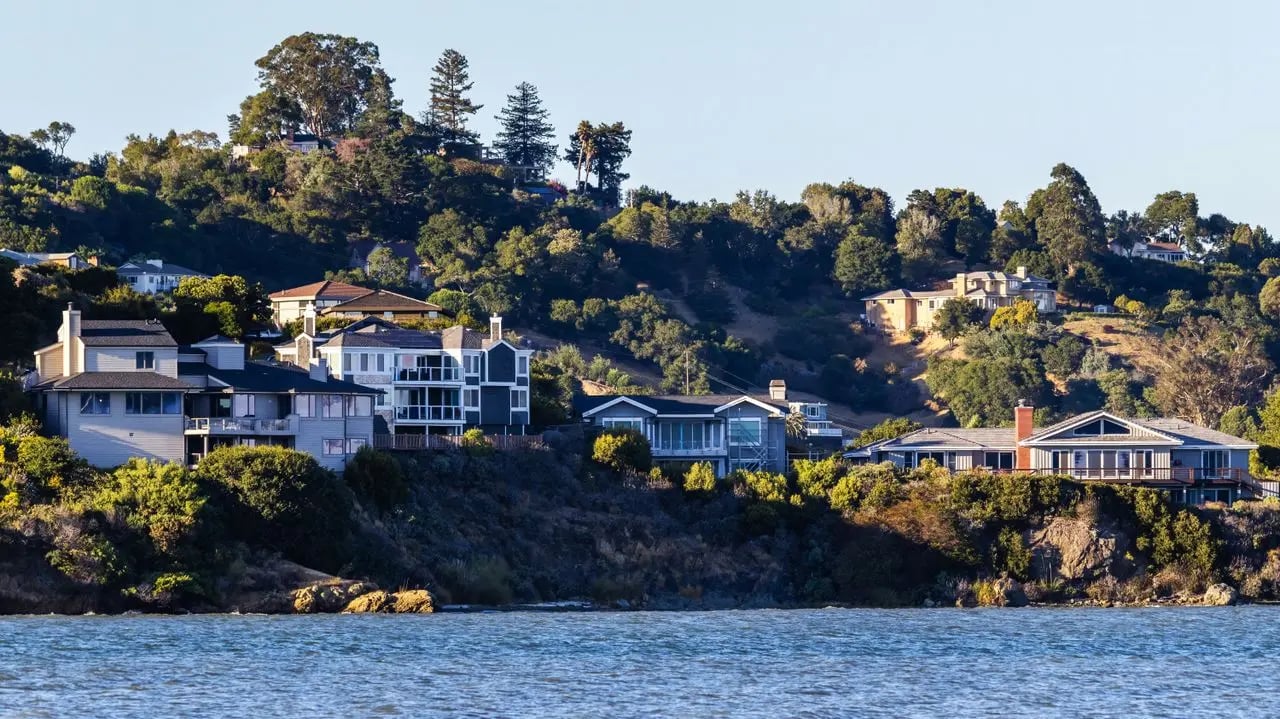
After waves of change caused by low mortgage rates, inflation, and slowed demand, the real estate market is now contending with a new challenge: insurance instability. In wildfire-prone areas, home insurance is becoming more expensive and harder to secure. From 2019 to 2024, more than 100,000 homeowners in California saw their insurance dropped, according to data from the Public Policy Institute of California.
This has left many homeowners blindsided—especially those who believed they were safely outside of high-risk zones. Just ask Claire O’Connor, a real estate agent from Los Angeles who lost her home in the Palisades fire just two months after being dropped by her insurer. She never thought her home was in danger—until it was gone.
Insurance is supposed to provide peace of mind, but for many, the recovery process is slow and full of obstacles. Instead of receiving immediate support, homeowners often face delays, paperwork, and unexpected rules about how payouts are handled.
O’Connor shared that even after receiving a check, she couldn’t use it freely. Because she still had a mortgage, the funds had to be co-signed with her lender and placed into escrow. This added another layer of stress during an already traumatic time.
Homeowners are often left navigating a maze of procedures, with each step dependent on documentation, approvals, and sometimes even upfront contractor quotes—before any rebuilding begins.
As both a victim of wildfire and an agent helping others recover, O’Connor offers a unique lens into the emotional and logistical burdens of disaster recovery. She’s seen how different insurers handle claims—some more cooperatively than others—but even those whose homes weren’t destroyed aren’t necessarily in a better position.
Many homeowners are being told to move back into homes that may be structurally intact but unsafe due to lingering fire damage or contamination. For families with children, that’s a major concern. Yet their policies often won’t cover extended living expenses unless the home is formally deemed uninhabitable.
Meanwhile, relocating isn’t always feasible. One of her clients, for example, pays just $3,000 per year for insurance in Arizona—but was quoted up to $50,000 annually for a home in Los Feliz. These extreme disparities are pushing buyers to reconsider where—and whether—they can afford to live in certain parts of California.
Soaring premiums are now a national issue, not just a California problem. Between 2019 and 2024, the average insurance premium in the U.S. increased by 24%—well beyond the inflation rate. States like Utah, Illinois, Arizona, and Pennsylvania all saw jumps between 44% and 59%, according to a recent Consumer Federation of America report.
Buyers need to be more informed and proactive than ever. Insurance is no longer a background detail—it’s a key financial consideration. O’Connor works with a trusted broker to help clients understand how things like fire-resistant features, distance from brush, and home materials affect their premiums.
She recommends looking at mitigation strategies early in the home search. Features like metal roofs or defensible landscaping can sometimes lower rates, but they’re not guaranteed solutions—especially in areas already classified as high-risk.
The days of treating home insurance like an afterthought are over. Today, it plays a pivotal role in determining where you can live and what it will cost to stay protected. If you're thinking of moving to Orange County, don’t make these decisions alone. At Whitestone Real Estate, I help clients make smart, informed choices in a rapidly changing market. Reach out today, and let’s make sure your next move is both exciting and secure.
Reference: Conte, A. (2025, May 11). My Home Burned Down in the Palisades Fire—Here’s What No One Tells You About Insurance. Realtor.com.
Home prices dipped nationwide in October 2026, but Orange County held firm. See what rates and rising inventory mean for buyers and sellers.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663