Why Today’s Housing Market Is Not About To Crash
Lisa Mailhot | May 17, 2023
Lisa Mailhot | May 17, 2023
There’s been some concern lately that the housing market is headed for a crash. And given some of the affordability challenges in the housing market, along with a lot of recession talk in the media, it’s easy enough to understand why that worry has come up.
But the data clearly shows today’s market is very different than it was before the housing crash in 2008. Rest assured, this isn’t a repeat of what happened back then. Here’s why.
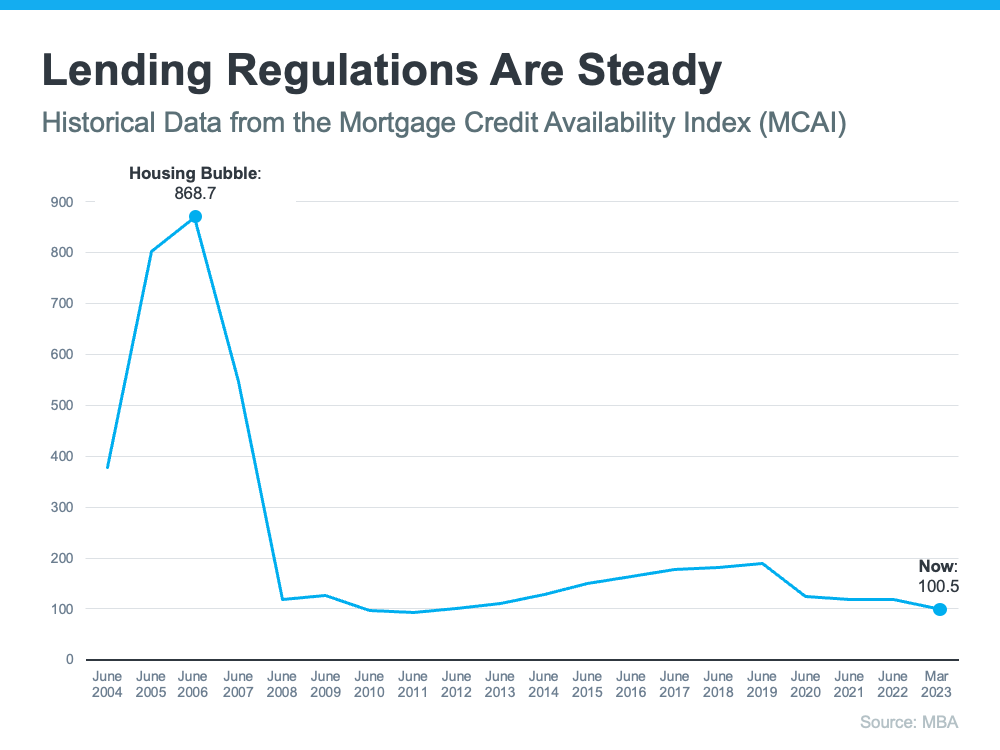
It was much easier to get a home loan during the lead-up to the 2008 housing crisis than it is today. Back then, banks had different lending standards, making it easy for just about anyone to qualify for a home loan or refinance an existing one. As a result, lending institutions took on much greater risk in both the person and the mortgage products offered. That led to mass defaults, foreclosures, and falling prices.
Things are different today as purchasers face increasingly higher standards from mortgage companies. The graph below uses data from the Mortgage Bankers Association (MBA) to show this difference. The lower the number, the harder it is to get a mortgage. The higher the number, the easier it is.
 Unemployment Recovered Faster This Time
While the pandemic caused unemployment to spike over the last couple of years, the jobless rate has already recovered back to pre-pandemic levels (see the blue line in the graph below). Things were different during the Great Recession as a large number of people stayed unemployed for a much longer period of time (see the red in the graph below):
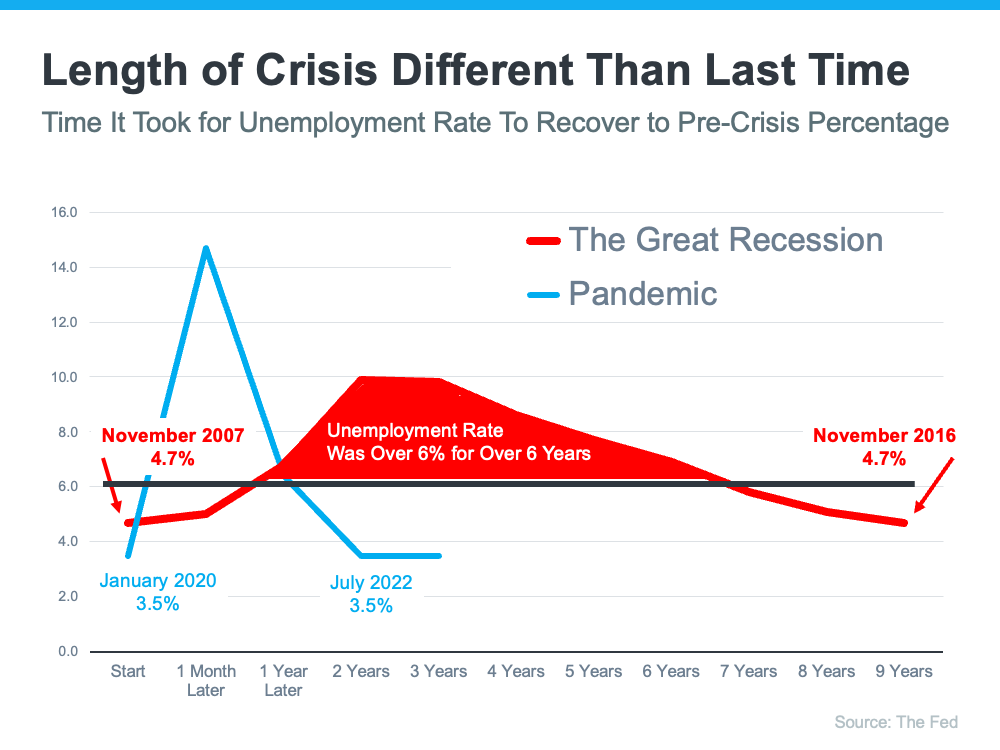
Here’s how the quick job recovery this time helps the housing market. Because so many people are employed today, there’s less risk of homeowners facing hardship and defaulting on their loans. This helps put today’s housing market on stronger footing and reduces the risk of more foreclosures coming onto the market.
There were also too many homes for sale during the housing crisis (many of which were short sales and foreclosures), and that caused prices to fall dramatically. Today, there’s a shortage of inventory available overall, primarily due to years of underbuilding homes.
The graph below uses data from the National Association of Realtors (NAR) and the Federal Reserve to show how the months’ supply of homes available now compares to the crash. Today, unsold inventory sits at just a 2.6-months’ supply. There just isn’t enough inventory on the market for home prices to come crashing down like they did in 2008.
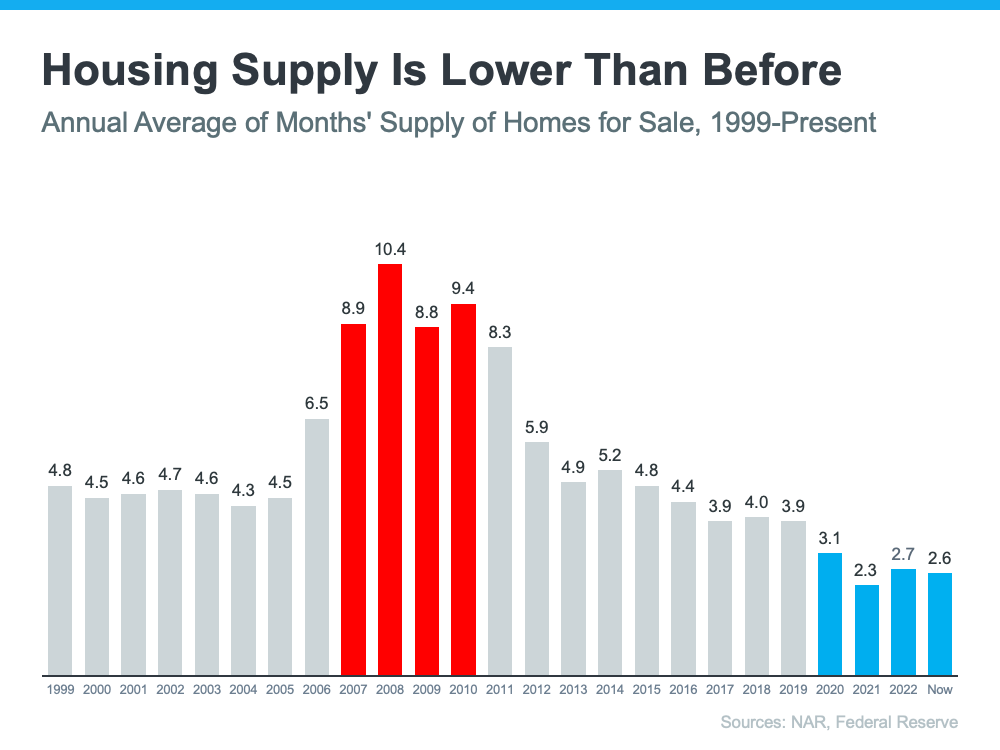
That low inventory of homes for sale helped keep upward pressure on home prices over the course of the pandemic. As a result, homeowners today have near-record amounts of equity (see graph below):
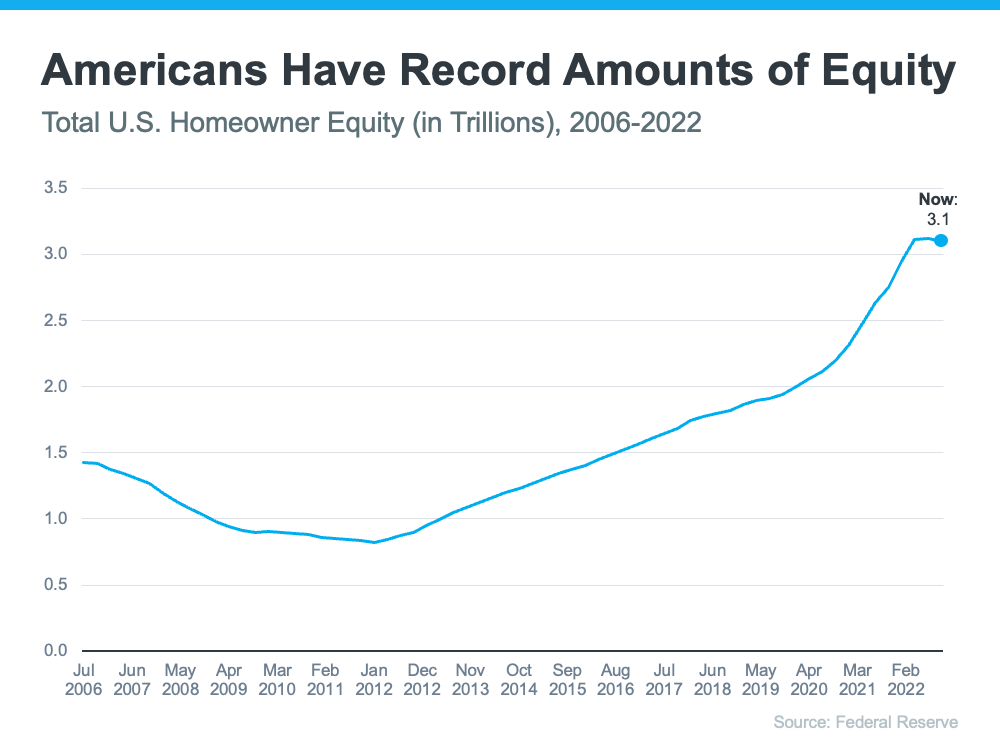
And, that equity puts them in a much stronger position compared to the Great Recession. Molly Boesel, Principal Economist at CoreLogic, explains:
“Most homeowners are well positioned to weather a shallow recession. More than a decade of home price increases has given homeowners record amounts of equity, which protects them from foreclosure should they fall behind on their mortgage payments.”
The graphs above should ease any fears you may have that today’s housing market is headed for a crash. The most current data clearly shows that today’s market is nothing like it was last time.
Home purchase cancellations hit a record high. Learn what it means for Orange County buyers and sellers and how to negotiate smartly.
Listings are up 7.4% while buyers retreat and sellers hold firm on price. Here is what it means for Orange County buyers and sellers.
Orange County inventory dipped as sales and delistings rose. See what the latest numbers mean for buyers and sellers heading into winter.
Home prices fell for a third straight week and payments dipped. See what it means for Orange County buyers and sellers and how to act now.
Mortgage rates are easing despite a looming December Fed hike. See what it means for Orange County buyers and sellers.
California’s Prop. 1 housing bond could fund 40,000 rentals and help 40,000 buyers. See what it means for Orange County buyers and sellers.
Record king tides and a Super El Niño are flooding Orange County and SoCal coasts. Here is where the water has hit and what comes next.
Pending sales hit a multi-year October low in Orange County, but equity keeps the market steady. See what buyers and sellers should know.
Housing costs are the top concern for young voters heading into the 2026 midterms. See what it means for Orange County buyers and sellers.
Let's find a time that suits you best to chat about your goals, show you how we work, and figure out how we can help you the most
Get In Touch With Lisa

Broker Associate
949-877-7087
124 Tustin Ave Suite 200, Newport Beach, CA 92663